The coverage question changes with the risk map
How much of Kern County's high-risk property stock has federal flood insurance? A newly released federal dataset supplies two sharply different answers: 24.5% under FEMA's mapped high-risk designation and 2.4% under First Street's modeled high-risk classification. What’s the Scoop With Broach extracted Kern's row from GAO's October 1 county workbook and compared both denominators, then checked the matching methodology and neighboring Central Valley counties.
The original county-level comparison establishes a 22.1-percentage-point difference in estimated National Flood Insurance Program coverage. It also identifies a detail that prevents a simple explanation: FEMA's designation covers 4.3% of Kern properties, while First Street's high-risk group covers a slightly smaller 3.8%. The lower modeled-risk coverage rate therefore cannot be explained simply by saying the model labels a larger share of Kern properties high risk.
The two classifications identify different groups, not interchangeable labels for the same set of properties. The public workbook does not reveal their property-by-property overlap in Kern. It cannot tell us which neighborhoods account for the difference, whether a particular home is insured, or whether either risk assessment is more accurate for a particular location.
Four denominators that should not be confused
The workbook separates the share of all properties classified as high risk from the share of each high-risk group carrying NFIP coverage. It also reports federal coverage among all properties. For Kern, that last figure is 1.3%. It is not the percentage of residents insured, the share of homeowners insured, or the proportion of high-risk properties insured.
FEMA's Special Flood Hazard Area designation uses a flood event with a 1% annual chance of being equaled or exceeded. GAO treated First Street flood scores of 4 through 10 as high risk because they roughly align with that probability threshold. Similar thresholds do not guarantee the same footprint: a regulatory map and a property-level model can classify different locations.
The 24.5% figure describes estimated NFIP coverage within the FEMA-designated group; 2.4% describes coverage within the First Street group. Subtracting either from 100 yields a share without estimated NFIP coverage in that group, not a verified share without any flood insurance. GAO's county table does not include private flood policies. Calling 97.6% of the modeled group wholly uninsured would go beyond these records.
| Measure | Share |
|---|---|
| All properties classified high risk by FEMA | 4.3% |
| All properties classified high risk by First Street | 3.8% |
| FEMA high-risk properties with NFIP coverage | 24.5% |
| First Street high-risk properties with NFIP coverage | 2.4% |
| All properties with NFIP coverage | 1.3% |
Neighboring counties show why one county's explanation cannot be assumed
We checked Kings and Tulare counties using the same columns and date. Their FEMA-group coverage rates sit near Kern's: 29.1% in Kings and 23.6% in Tulare, compared with Kern's 24.5%. The modeled-group coverage rates are much lower in all three: 2.9%, 7.0% and 2.4%, respectively.
But the risk-group sizes behave differently. First Street classifies a larger share of properties as high risk than FEMA does in both Kings and Tulare. Kern reverses that relationship. That is the value of checking the denominator locally: an explanation based on a model identifying more high-risk properties may fit the size comparison in neighboring counties, but it does not describe Kern's published row.
This is a three-county comparison, not a statewide ranking or a causal test. Different flood hazards, development patterns, insurance markets and property records could affect the results. The workbook alone cannot separate those influences, and it provides no basis to accuse local officials, lenders or property owners of violating insurance requirements.
| County | FEMA high-risk share | First Street high-risk share | NFIP within FEMA group | NFIP within First Street group |
|---|---|---|---|---|
| Kern | 4.3% | 3.8% | 24.5% | 2.4% |
| Kings | 1.5% | 4.3% | 29.1% | 2.9% |
| Tulare | 13.2% | 22.8% | 23.6% | 7.0% |
An estimate assembled from records with different dates
The underlying report's methods appendix dates First Street property characteristics to January 2024 and its flood-risk data to March 2025. GAO matched those records with NFIP policies active April 30, 2026. These figures are therefore a historical estimate released October 1, not a real-time inventory of Kern properties and insurance on October 5.
Nationally, GAO matched 79.2% of NFIP contracts to a First Street property record. For county-specific coverage estimates, it divided the matched coverage rate by the county-specific match rate for all contracts. That adjustment matters: the workbook's rates are not simply the number of matched policies divided by properties, and our analysis did not independently recreate GAO's property-level linkage.
GAO found that unmatched policies nationally were more likely to be in FEMA high-risk areas and had higher full-risk premiums than matched policies. It cautioned that its modeling could understate the association between flood risk, FEMA designation and NFIP purchase. The county download does not provide a Kern-specific uncertainty interval, match rate or list of unmatched properties. We cannot quantify how much that limitation changes Kern's 22.1-point difference.
What oversight can—and cannot—take from the comparison
The accountable question is whether a single mapped-zone insurance figure adequately describes protection across the county's different measures of flood risk. These records show that it does not: changing the risk definition produces a substantially different estimate. Any public presentation of a Kern coverage rate needs to state which property group it measures and that private insurance is excluded.
The national report also records disagreement over policy remedies. USDA's Rural Housing Service supported better property-risk disclosure but raised affordability and transaction-burden concerns about expanding insurance requirements. GAO acknowledged affordability concerns and discussed assistance options. Those positions concern national policy; they are not a response from Kern County to this analysis or evidence that a new local mandate has taken effect.
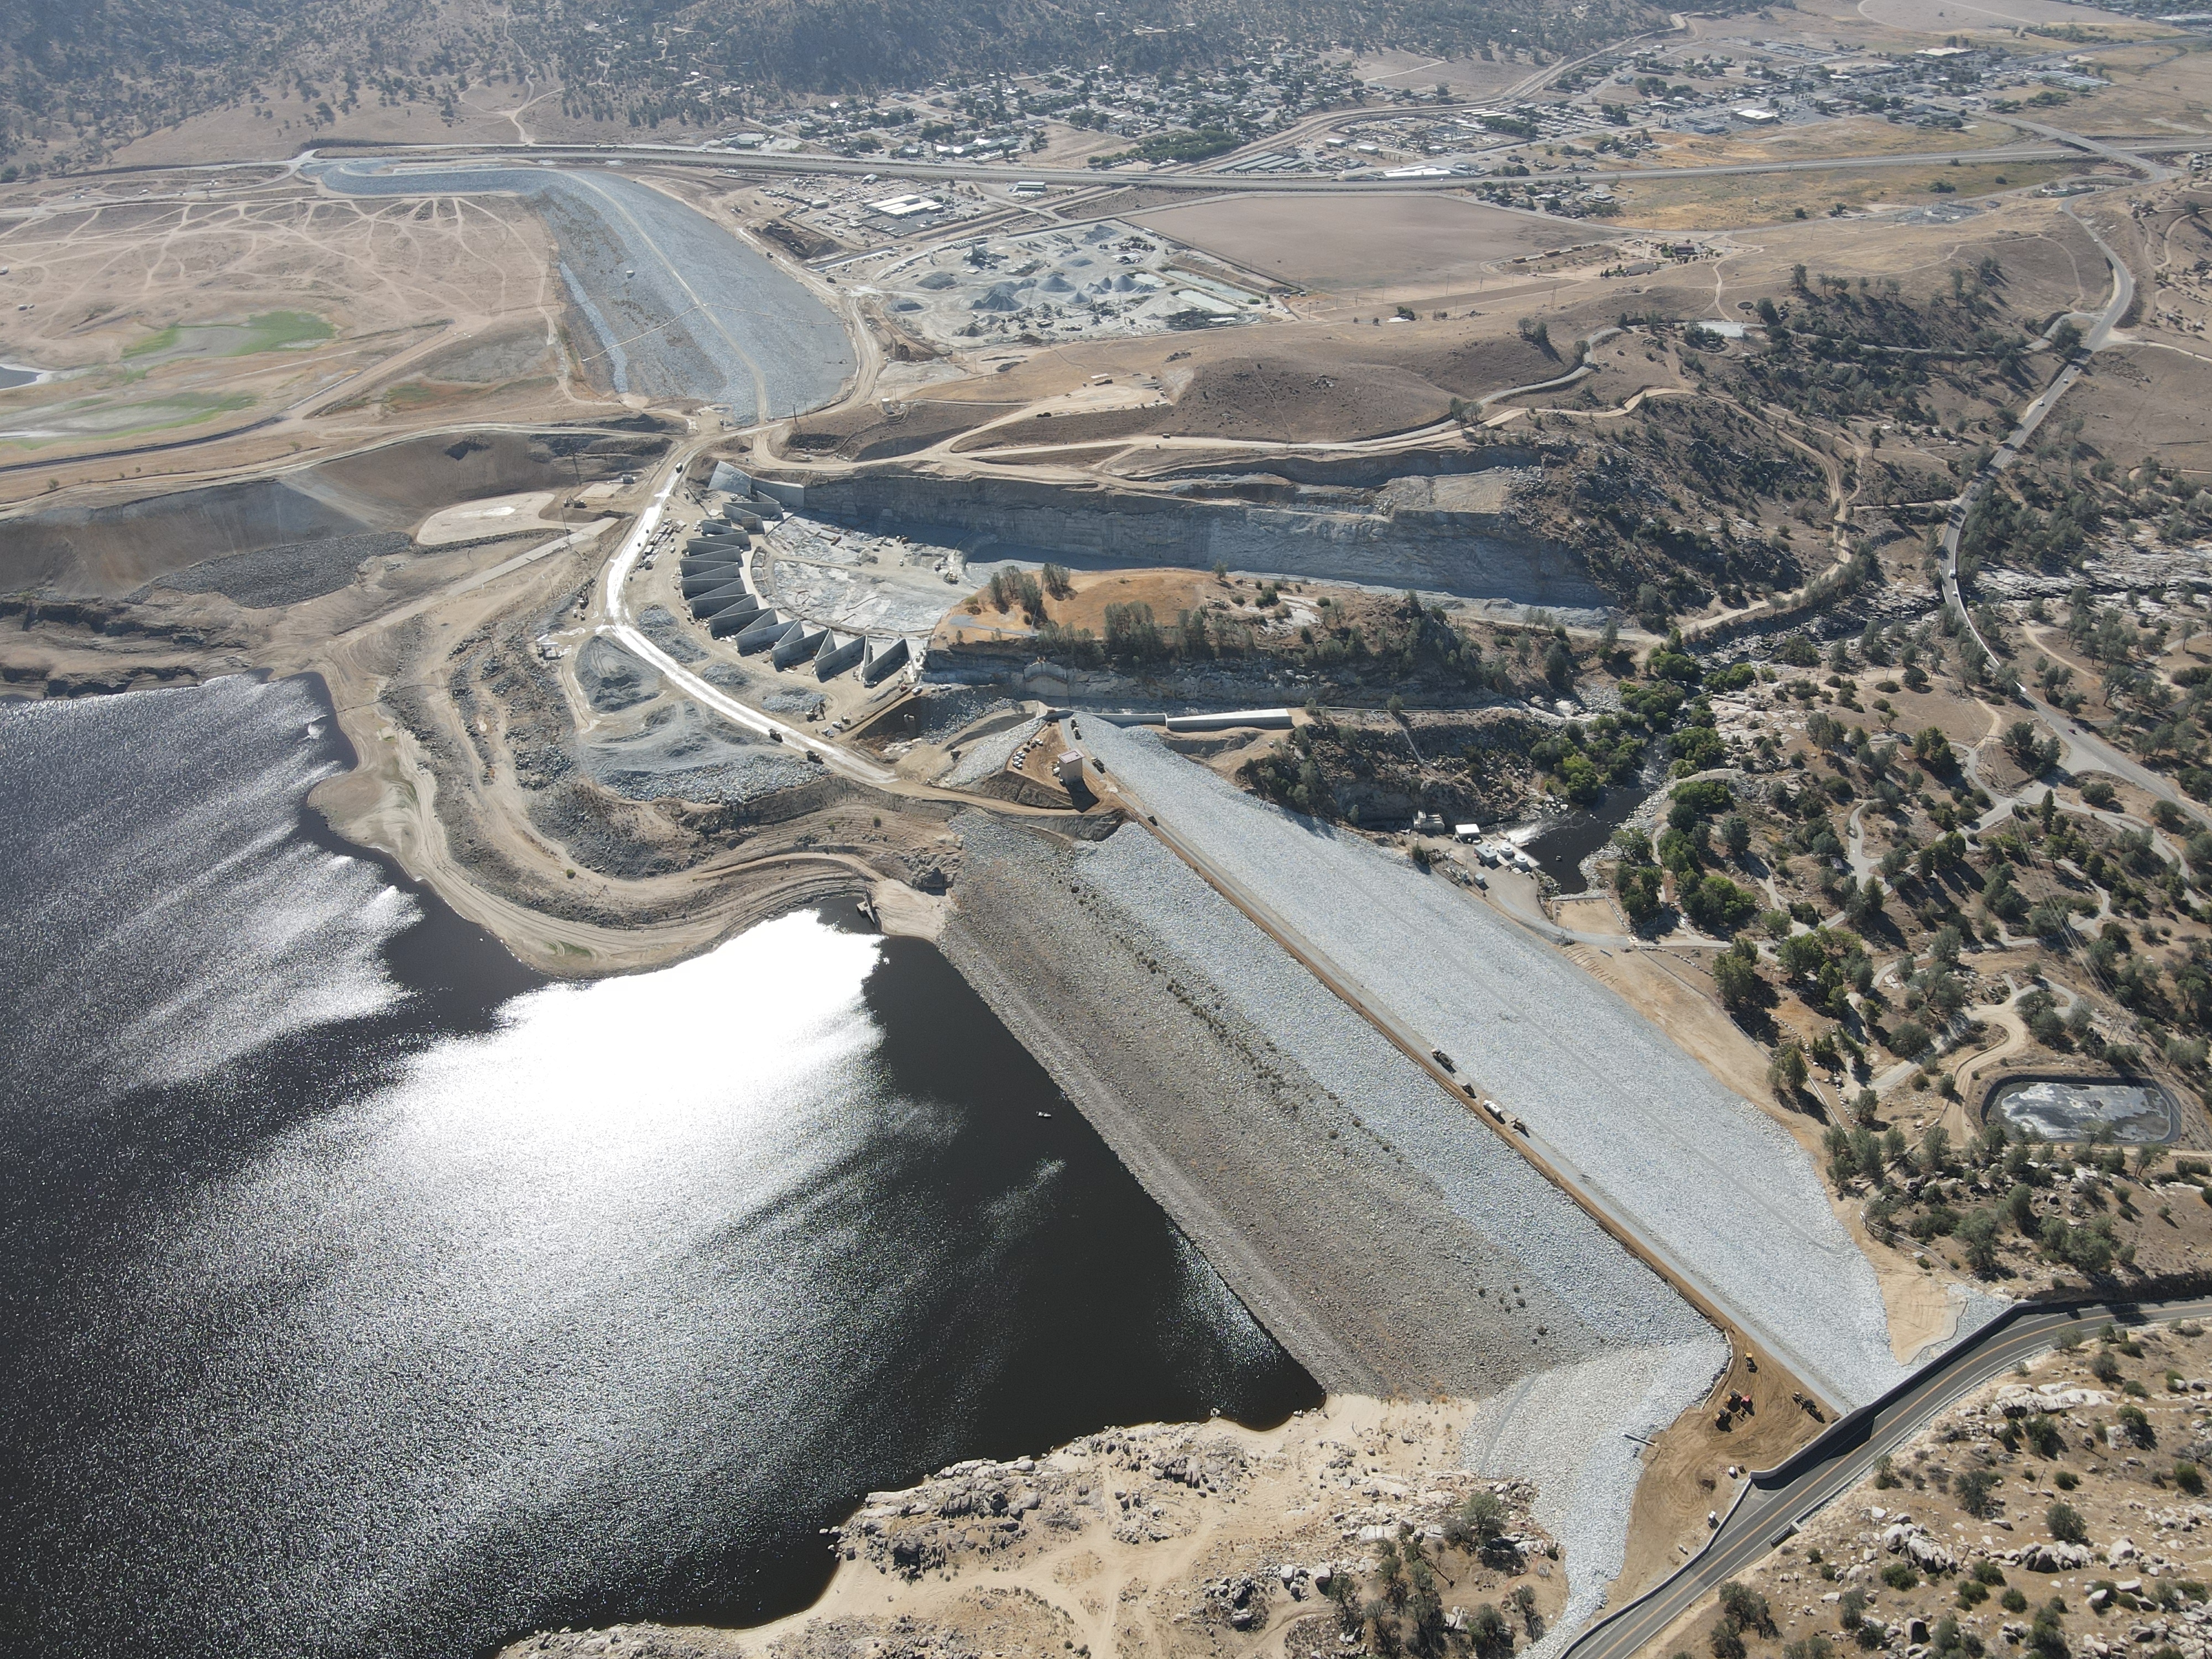
For this investigation, we examined the original workbook's Kern, Kings and Tulare rows, checked percentage units and calculated 24.5 minus 2.4. We read GAO's risk definitions, matching adjustments and limitations rather than treating the interactive map as a count of uninsured households. The result identifies a consequential local measurement gap. It does not predict the next flood, judge the safety of Isabella Dam, establish individual insurance obligations or claim interviews that did not occur.
Sources and further reading
GAO-27-108012, October 1, 2026: full report, methodology and agency comments ↗
GAO downloadable county dataset, Kern County FIPS 06029 ↗